Key Points
- The Upper Tribunal has ruled that the First-tier Tribunal got things wrong legally in the capital allowances case concerning Mersey Docks Harbour Company.
- It relates to £57.1 million investment in a new quay wall at Liverpool2, the deep-water container terminal operated by the Port of Liverpool.
- MDHC contended that their investment should be regarded as capital allowance for plant and machinery.
- On appeal, HMRC contended that the First-tier Tribunal treated the quay wall as premises (rather than apparatus) and a List C exception did not apply.
- The Upper Tribunal agreed that the First-tier Tribunal took the right general approach to this matter but erred in how they applied it, specifically in their consideration of the function of the quay wall and its primary purpose.
- There were also flaws in the List C exception for ‘machinery’ and the application of the necessity test.
- It will now return to the First-tier Tribunal where a new panel will reconsider their ruling rather than rehear the case in full.
- All of the findings of facts previously determined by the First-tier Tribunal will be carried forward apart from a small number of exceptions.
- According to Pinsent Masons specialists Jake Landman and Andrew McCarthy, the remittal means another delay and underlined the importance of receiving early capital allowances advice for large scale infrastructure investments.
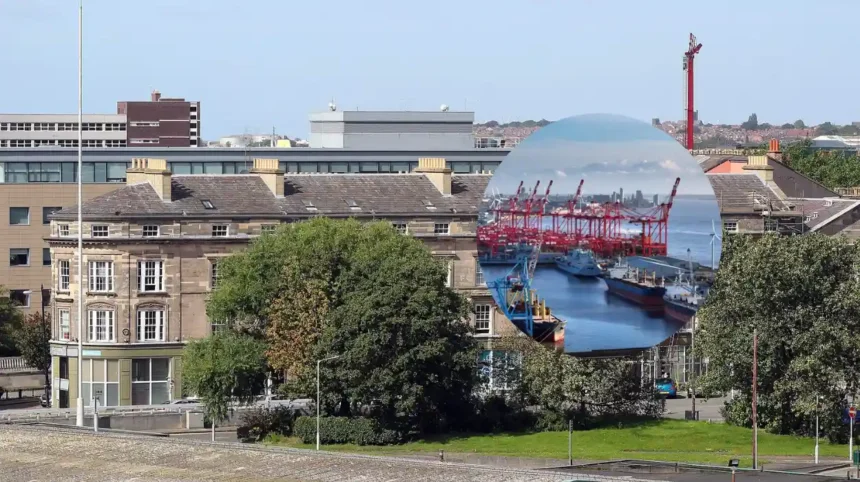
Liverpool (Liverpool standard) November 12, 2026 — A tax tribunal has been asked to reconsider whether the operator of the Port of Liverpool can claim capital allowances on £57.1 million spent on a new quay wall, after judges found that the original decision contained material errors of law. As reported by Pinsent Masons, the dispute concerns Mersey Docks Harbour Company (MDHC), which built the quay wall as part of Liverpool2, a new deep-water container terminal at the Port of Liverpool.
- Key Points
- What is the Liverpool port capital allowances dispute?
- Why is the tribunal reconsidering the case?
- What errors did the Upper Tribunal identify?
- How did the List C exception affect the ruling?
- What happens next for MDHC and HMRC?
- What have tax experts said?
- Background of the development
- Prediction: how this development can affect port operators
What is the Liverpool port capital allowances dispute?
The Liverpool port capital allowances dispute centres on whether MDHC’s expenditure on the quay wall should be treated as spending on “plant or machinery” for UK corporation tax purposes. MDHC argued that the construction costs qualified for capital allowances, a form of tax relief available to businesses that spend money on capital assets used in their business.
Under UK tax law, capital allowances can include relief for expenditure on the provision of plant or machinery. However, the rules contain exclusions and exceptions that can determine whether particular infrastructure spending qualifies.
One exclusion applies to expenditure on “a dock, harbour, wharf, pier, marina or jetty or any other structure in or at which vessels may be kept, or merchandise or passengers may be shipped or unshipped”. The dispute turned in part on whether the quay wall fell within a List C exception for certain kinds of machinery, which could make the expenditure eligible for capital allowances relief.
Why is the tribunal reconsidering the case?
The Upper Tribunal has decided that the First-tier Tribunal’s original ruling must be set aside because it made errors of law. The original tribunal had found that MDHC’s expenditure on the quay wall fell within the List C exception, meaning it should be treated as expenditure on the provision of plant or machinery and therefore qualified for capital allowances.
As reported by Pinsent Masons, HMRC appealed that decision to the Upper Tribunal. HMRC raised two broad arguments: first, that the First-tier Tribunal was not entitled to conclude that the quay wall was apparatus rather than premises, including because it applied the wrong legal test; and second, that the tribunal erred in law when it concluded that the List C exception was engaged.
The Upper Tribunal accepted that the First-tier Tribunal had chosen the correct “evaluative multi-factorial approach” for deciding how the quay wall should be classified. However, it found that errors arose in the way that approach was carried out.
What errors did the Upper Tribunal identify?
The Upper Tribunal identified several problems with the original tribunal’s reasoning. It said the First-tier Tribunal misdirected itself when it drew an analogy between the dry dock considered in the earlier Barclay Curle case and the quay wall and its associated cranes as a “composite asset”. According to the Upper Tribunal, the First-tier Tribunal should instead have considered the functions of the quay wall by itself.
The Upper Tribunal also found that the First-tier Tribunal did not carry out a sufficient multi-factorial analysis of the quay wall’s functions. As a result, it concluded that the reasoning used to explain why the quay wall was plant rather than premises was flawed.
In addition, the Upper Tribunal said the First-tier Tribunal failed to give adequate reasons when assessing the quay wall’s primary purpose. It said the tribunal did not sufficiently explain why it preferred the evidence of one expert over another, leaving its reasoning on the structure’s predominant purpose unclear.
How did the List C exception affect the ruling?
The Upper Tribunal also found problems with the First-tier Tribunal’s approach to the List C “machinery” exception. It said the original tribunal erred when it applied a “test of necessity” in finding that expenditure on the quay wall was necessary for the cranes to be installed.
Although the First-tier Tribunal referred to case law stating that a necessity test was not required, the Upper Tribunal considered that the tribunal appeared to apply one in its reasoning.
The Upper Tribunal also considered the effect of a later UK Supreme Court decision in a separate case involving Orsted. That judgment set a narrower test for determining when expenditure can be regarded as expenditure “on” the provision of plant or machinery, requiring a close connection between the expenditure and the plant provided.
The Upper Tribunal considered that, in that context, the First-tier Tribunal had applied the wrong test to its assessment. It noted that the Supreme Court judgment had not been available at the time of the original First-tier Tribunal decision.
What happens next for MDHC and HMRC?
Because of the legal errors, the Upper Tribunal said the First-tier Tribunal’s decision must be set aside. However, it said it was not in a position to remake the decision itself and therefore remitted the case to the First-tier Tribunal for reconsideration by a new panel.
The reconsideration will not involve a full rehearing. Findings of fact from the original decision will stand, except for certain specified items that the new panel will need to revisit.
The outcome remains significant for MDHC because the central question whether the £57.1 million quay wall expenditure qualifies for capital allowances has not yet been finally determined. The new tribunal panel will reconsider the case in light of the Upper Tribunal’s findings on the legal errors.
What have tax experts said?
Tax law expert Jake Landman of Pinsent Masons said the Upper Tribunal commented that there appeared to be no good reason for the delay in the First-tier Tribunal releasing its original decision. However, he said the Upper Tribunal was not satisfied that the delay materially contributed to the errors or that HMRC was right to argue that the delay meant the decision could not stand.
“The fact that the case has now been remitted for reconsideration by a different FTT means that there will be further delay and a need to revisit certain factual material even longer after the original FTT hearing, which seems less than ideal,” Landman said, as reported by Pinsent Masons.
Andrew McCarthy, also a tax law expert at Pinsent Masons, said the capital allowances treatment of large infrastructure projects and their components has always been complex. He added that, at a time of comparatively high interest rates affecting project viability, it will be increasingly important for businesses to obtain early and substantive capital allowances advice.
Background of the development
MDHC constructed the quay wall as part of Liverpool2, a new deep-water container terminal at the Port of Liverpool. The company argued that the £57.1 million construction cost should qualify for capital allowances because it related to the provision of plant and machinery.
Capital allowances are a UK tax relief that may be available where a company spends money on capital assets for use in its business. The legal issue in this case was whether the quay wall should be classified as plant or machinery, or as premises, and whether it fell within the relevant List C exception.
The First-tier Tribunal initially supported MDHC’s position, finding that the expenditure qualified for relief. HMRC then appealed to the Upper Tribunal, which has now required the case to be reconsidered because of errors in the original tribunal’s legal reasoning.
Prediction: how this development can affect port operators
For port operators, infrastructure developers and businesses undertaking large construction projects, the remittal highlights the legal uncertainty that can surround capital allowances claims for major assets. The case shows that even where a tribunal accepts a broad multi-factorial approach, the detailed reasoning used to classify infrastructure as plant, machinery or premises can determine whether tax relief is available.
For MDHC, the immediate effect is further procedural delay and the need for a new tribunal panel to reconsider specified aspects of the case. The company’s original factual findings will largely remain in place, but the legal analysis underpinning its capital allowances claim will be examined again.
For the wider ports and infrastructure sector, the decision may encourage businesses to document the function, design and intended use of major assets more carefully from the outset. As Pinsent Masons’ Andrew McCarthy noted, early and substantive capital allowances advice is likely to become more important for large projects, particularly where financing costs are affected by comparatively high interest rates.